Chuan Park
31 units available
$2,555–$2,616 psf
97% sold
Hougang Central GLS is an upcoming launch in D19 (OCR, North-East region) — GLS site: Hougang Central. Everything below is compiled from matched transactions, URA tender data and public sources.
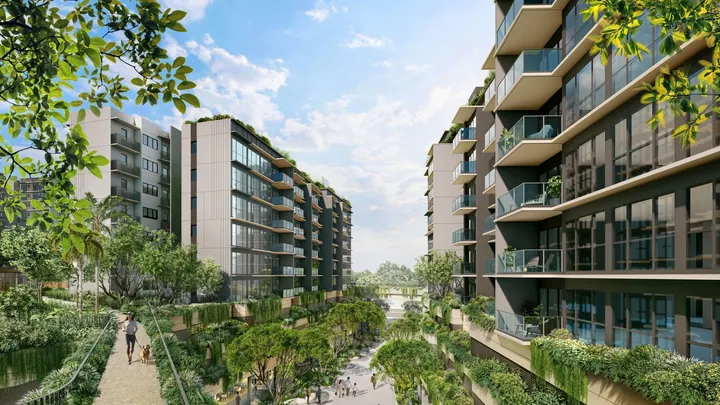
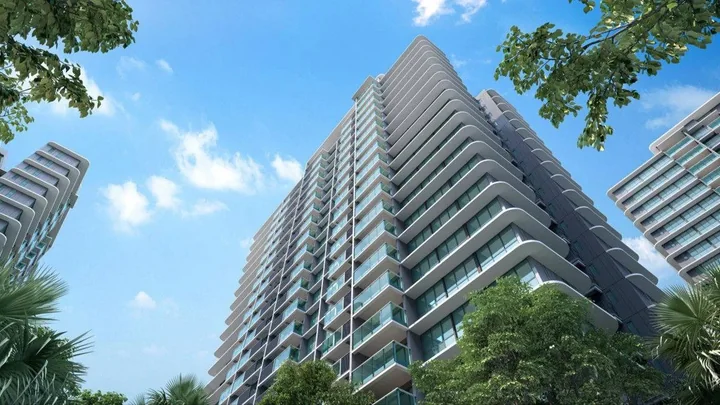
Artist impressions and marketing images are supplied by the developer and compiled by PropertyInsider.sg. They are indicative only, may show upgraded finishes or landscaping that is not part of the standard specification, and are not a representation of the completed development. Verify the specification against the developer’s sales documents.
Hougang Central GLS is an upcoming 835-unit 99-year leasehold integrated mixed-use development in D19 (OCR, North-East region), developed by CapitaLand / UOL, with completion expected in 2031.
The site sits about 0.14 km in a straight line from Hougang (NE14), roughly 2 minutes on foot. It has not launched. Our estimated launch range is $2,580–$2,920 psf (est.), anchored on an estimated breakeven of $2,247 psf ppr — see the estimate and its cost stack below.
This overview is generated from PropertyInsider.sg’s tracked record for this project — URA tender data, matched caveat transactions and public filings — not from developer marketing material. Figures as at 2 Sept 2026. Anything marked (est.) is our estimate and is explained where it appears.
The full tracked record for Hougang Central GLS, field by field. Every figure here is repeated in context further down the page, with its source and its caveats.
Compiled by PropertyInsider.sg from URA tender records, matched caveat transactions and public filings; last refreshed 2 Sept 2026. Values marked (est.) are our estimates — the launch-price method is set out in our pricing methodology.
PropertyInsider’s estimated launch price for this site, and the indicative quantum that range implies at typical unit sizes.
Breakeven is the estimated total development cost divided by gross floor area, in dollars per square foot per plot ratio — the same basis as the land rate. Cost stack: PropertyInsider.sg cost model, land awarded 14 Jan 2026. Figures are estimates (est.), not the developer’s accounts.
Estimates are anchored on the site's estimated breakeven rate and a measured developer margin band; developers make final pricing decisions. Indicative quantums apply the estimated psf range to typical unit sizes — not a price list.
Where Hougang Central GLS sits on the map, with its district, market segment and nearest station on the rail network. The nearest MRT station is Hougang (NE14), about 0.14 km away in a straight line, roughly 2 minutes on foot. The dashed rings on the map mark straight-line 1 km and 2 km radii from the site.
Hougang Central GLS is located at 1.37255, 103.89197 in D19, Singapore. The interactive map loads when this section comes into view.
Open this location in Google Maps·Every tracked launch on one map·Primary schools map
The marker is an approximate site centroid compiled by PropertyInsider.sg, not a surveyed boundary. Station distances are straight-line, measured from the site centroid to the midpoint of a station’s published exits (LTA MRT/LRT exits dataset) — not the distance to the nearest exit, and not a walking route. Walking times are an estimate only and are omitted beyond 2 km. Base map tiles are © OneMap / Singapore Land Authority. Verify exact addresses, boundaries and journey times with the developer or on OneMap.
The places that actually shape how this address lives day to day — stations, schools, food, shops, green space, healthcare and the nearest employment nodes — with a straight-line distance and an estimated walk and drive for each. Use the buttons below to hide a category on the map above and in this table at the same time.
| Place | Straight line | On foot | By car |
|---|---|---|---|
| Hougang MRTNE14 · North East Line | 0.14 km | 2 min | — |
| Hougang MallShopping mall | 0.20 km | 3 min | — |
| Punggol CCCommunity club | 0.20 km | 3 min | — |
| Kang Kar MallShopping mall | 0.27 km | 4 min | — |
| Montfort Junior SchoolP1 vacancies available | 0.27 km | 4 min | — |
| Montfort Secondary SchoolSecondary · Boys | 0.37 km | 6 min | — |
| Hougang PolyclinicPublic polyclinic · NHG Health | 0.44 km | 7 min | — |
| Hougang Sport CentreActiveSG sport centre | 0.49 km | 7 min | — |
| Holy Innocents' High SchoolSecondary | 0.51 km | 8 min | — |
| CHIJ Our Lady of the NativityModerate P1 demand | 0.64 km | 10 min | — |
| Hougang VillageShopping mall (location approximate) | 0.67 km | 10 min | — |
| Holy Innocents' Primary SchoolVery high P1 demand | 0.67 km | 10 min | — |
| Punggol Primary SchoolHigh P1 demand | 0.70 km | 10 min | — |
| Hougang CCCommunity club | 0.87 km | 13 min | 3 min |
| Hougang Green Shopping MallShopping mall | 0.87 km | 13 min | 3 min |
| Punggol ParkPark · 16 ha | 0.89 km | 13 min | 3 min |
| Yio Chu Kang Primary SchoolP1 vacancies available | 0.92 km | 14 min | 3 min |
| Xinmin Secondary SchoolSecondary | 0.99 km | 15 min | 3 min |
| Ci Yuan Hawker CentreHawker centre · 40 cooked-food stalls | 1.05 km | 16 min | 3 min |
| Buangkok Hawker CentreHawker centre · 38 cooked-food stalls | 1.16 km | 17 min | 3 min |
| Buangkok MRTNE15 · North East Line | 1.17 km | 18 min | 3 min |
| Ranggung LRTSE5 · Sengkang LRT | 1.42 km | 21 min | 4 min |
| Institute of Mental HealthPublic psychiatric hospital | 1.47 km | 22 min | 4 min |
| Kovan Hougang Market and Food CentreHawker centre · 66 cooked-food stalls | 1.64 km | 25 min | 5 min |
| DPS International SchoolInternational school | 2.23 km | — | 6 min |
| International French School (Singapore)International school | 2.74 km | — | 8 min |
| Paya Lebar iParkBusiness and innovation park | 2–5 km | — | 10–20 min |
| Punggol Digital DistrictBusiness and innovation park | 2–5 km | — | 10–20 min |
| The Culinary Institute of America SingaporeOverseas university partner nearest — beyond 3 km | 5.13 km | — | 15 min |
| Downtown (CBD and Marina Bay)Central business district | 10–15 km | — | 30–45 min |
No categories selected. Pick one above, or .
30 places shown Every distance here is a straight line between two points, not a walking or driving route, and each place is a single representative coordinate — a park or a business district is one point, not its nearest entrance. Treat them as a ranking of what is close, not as journey times. Verify anything you are relying on with OneMap. Primary-school bands carry their own MOE caveat in the schools section below.
Distances are straight lines from an approximate site centroid compiled by PropertyInsider.sg, not walking or driving routes, and each place is a single representative coordinate. Walking times are an estimate only, at an 80 m/min pace with a 1.2× allowance for street routing, and are omitted beyond 2 km. Verify anything you are relying on with OneMap.
Matched developer-sale transactions by bedroom type: average price, average psf, transacted price range, size range and units sold. Entry prices usually reflect lower floors or less ideal facings.
| Type | Avg price | Avg psf | Transacted range | Size range | Units sold | Available |
|---|
Site plans are developer marketing material compiled by PropertyInsider.sg. Block positions, unit counts, facing and facility placement are indicative and can change between the marketing plan and the approved building plan. Confirm against the developer’s sales documents and the approved plans before relying on a stack, facing or distance.
| Date | Unit | Type | Size | Price | Price psf |
|---|
Capital appreciation context for Hougang Central GLS: what sellers of completed condos in the same district actually realised on 17,946 matched buy-and-sell pairs (March 1995 to October 2026), including the 5.1% that sold at a loss.
Quarterly median exit psf of all matched resales, profitable and not, March 1995 to October 2026. Quarters with fewer than 5 exits carry no point; lines bridge to the next qualifying quarter. Source: URA caveat data, matched pairs.
Completed condos in D19 with at least 20 matched exits — the closest historical read on what this location has delivered. Ranked by median annualised return across every exit, not only the profitable ones.
Map of the 10 projects ranked below. Each pin is labelled with that project’s median annualised return.
| Project | TOP | Exits | Profitable | Median ann. return | Median hold | Median gain | Avg psf |
|---|---|---|---|---|---|---|---|
| Hundred Palms Residences | 2019 | 138 | 100.0% | 10.4% p.a. | 7.9y | $990k | $1,864 |
| Treasure Crest | 2018 | 193 | 100.0% | 8.7% p.a. | 7.7y | $749k | $1,458 |
| The Vales | 2017 | 266 | 100.0% | 7.4% p.a. | 6.8y | $522k | $1,544 |
| Kovan Melody | 2006 | 692 | 100.0% | 7.1% p.a. | 6.9y | $548k | $1,954 |
| Rivercove Residences | 2020 | 133 | 100.0% | 6.9% p.a. | 7.8y | $644k | $1,620 |
| The Terrace | 2017 | 298 | 98.7% | 6.9% p.a. | 7.4y | $568k | $1,439 |
| Bellewaters | 2017 | 320 | 99.4% | 6.7% p.a. | 7.6y | $595k | $1,449 |
| The Quartz | 2009 | 561 | 99.3% | 6.2% p.a. | 7.4y | $431k | $1,656 |
| The Amore | 2016 | 175 | 99.4% | 6.0% p.a. | 7.0y | $463k | $1,443 |
| Kovan Residences | 2011 | 404 | 98.5% | 5.9% p.a. | 7.2y | $475k | $1,019 |
Projects in the same district with at least 20 matched exits, ranked by median annualised return across every exit — profitable and not. Median gain is gross, before stamp duties, legal and agent fees, mortgage interest and renovation. Realised outcomes of past projects are context, not a prediction for this launch. Full dataset: resale exit dashboard.
What the developer paid for this site, ranked against the sites most like it — same market segment and planning region where we have enough of them, widening only if we do not. Land is the largest single input into a launch price and it is fixed two to three years before the show flat opens. Every tracked site sits on the land cost tracker.
MOE primary schools within a straight-line 1km and 2km of this project, with each school's P1 demand tier and phase-by-phase oversubscription ratios from the last completed registration exercise. An address inside a school's 1km band ranks highest whenever that school ballots. Explore every school on the primary schools map.
Map of Hougang Central GLS and the 11 primary school(s) inside its straight-line 1km and 2km rings. It loads when this section scrolls into view; every school is listed below with its distance.
Phase chips show applicants per place: 1.00× or under every applicant placed, 1.01–1.50× oversubscribed, above 1.50× heavily oversubscribed. Distances are straight-line estimates computed from project and school coordinates and shown to 2 decimal places — they are not the official home-school distance. Walking times use the same model as the nearby-places table above: 80 m/min with a 1.2× allowance for street routing, omitted beyond 2 km. For P1 registration, verify the exact 1km/2km status with the OneMap School Query tool, which applies MOE’s official measurement. No guarantee of accuracy; school demand tiers reflect the 2026 P1 exercise and can change year to year. The tier is read from Phase 2C alone — the round for children with no family link to the school, and the only one where home distance decides who gets in. Very high demand means the 2C ballot cut into citizens within 1km AND at least 1.5 applicants turned up per place. Full map and methodology: primary schools near new launches.
Other tracked launches and GLS sites in D19 or the same segment and region.
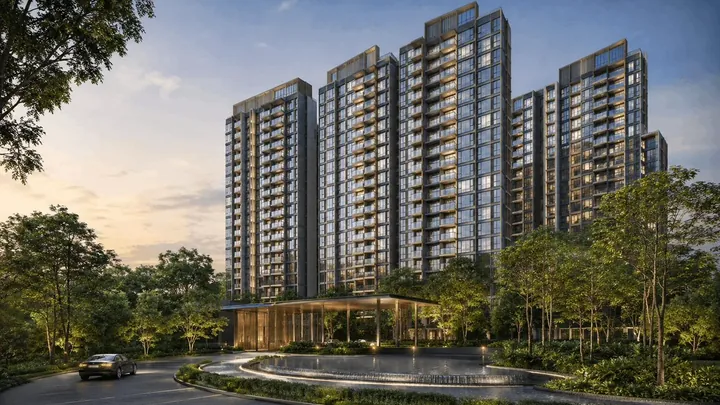
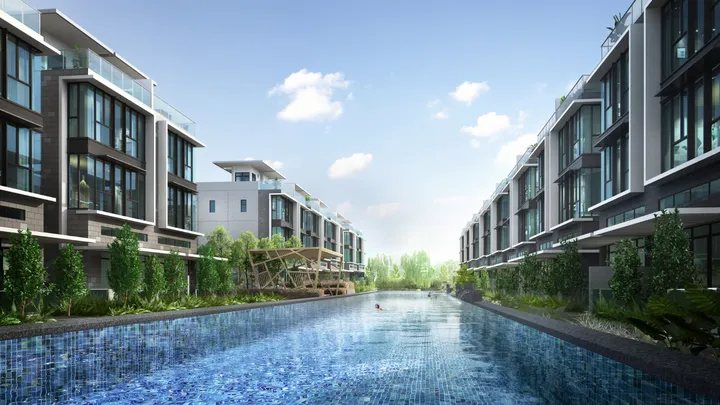
Hougang Central is a planned scheme of about 835 homes and shops in District 19. It replaces the current Hougang Bus Interchange at Hougang Avenue 10. The lease is 99 years. The developers are CapitaLand Development, UOL Group, Singapore Land Group and Kheng Leong. CapitaLand Integrated Commercial Trust takes the retail. The site was awarded on 14 January 2026 at $1,500,738,338, or $1,179 psf ppr. Preview is targeted for Q2 2027 (est.), with keys around 2031 to 2032 (est.).
Two facts separate it from the rest of the pipeline outside the central region. First, the homes sit on the station, not near it. The scheme is built over Hougang MRT (NE14) and a rebuilt bus interchange. Hougang also becomes a two-line interchange when the Cross Island Line opens in 2030. Second, the shops below are not a developer’s podium to sell off unit by unit. Roughly 300,000 sq ft of shop space will be owned and run by a listed trust, for good. That is a different kind of commitment to the address than a sales gallery makes.
An interchange is a fact. A price is a decision. Three questions decide this one. What does $1,179 psf ppr force the developer to charge? Does that number clear the cash a Hougang flat actually releases? And what has the nearest scheme of this type in the corridor really done for the people who bought it?
$1,179 psf ppr is the highest rate ever paid for a mixed-use state site outside the central region. That is about 20% above Chencharu Close and a third above Tampines Avenue 11, the two closest comparisons. The premium is not a mystery. Both of those sites carried a bus interchange. Neither carried an MRT station, an interchange rebuild and a 300,000 sq ft mall in one tender. What a buyer needs to know is not whether the developer overpaid, but where that land number lands the launch price.
| Site (planning area) | Awarded | Land use | psf ppr | vs Hougang Central |
|---|---|---|---|---|
| Hougang Central (Hougang, D19) | Jan 2026 | Commercial & residential | $1,179 | Baseline |
| Tampines Ave 11 — Parktown Residence (Tampines, D18) | Jul 2023 | Commercial & residential | $885 | −25% |
| Chencharu Close (Yishun, D27) | Sep 2025 | Commercial & residential | $980 | −17% |
| Tampines Street 94 (Tampines, D18) | Oct 2024 | Commercial & residential | $1,004 | −15% |
| Lakeside Drive (Jurong West, D22) | Jun 2025 | Residential with 1st-storey commercial | $1,132 | −4% |
| Chuan Grove (Serangoon, D19) | Sep 2025 | Residential | $1,331 | +13% |
| Chuan Grove (Serangoon, D19) | Jul 2025 | Residential | $1,376 | +17% |
The two Chuan Grove rows are the useful corrective to the “record land price” headline. Both sit in the same district. Both are plain housing plots, with no mall and no interchange to build. And both cost more per plot ratio than Hougang Central did. A record for one type of site is not a record for the district.
Land is one line in the cost stack. Add construction, finance, professional fees and marketing to the $1,179 psf ppr land cost. That gives an estimated breakeven of about $2,247 psf ppr. Applying the 1.15–1.30 margin band we use on every project on this site gives an indicative launch range of $2,580–$2,920 psf. The full working is in our pricing methodology. Applied to typical layouts, a 700 sq ft two-bedroom lands at roughly $1.81M to $2.04M. A 950 sq ft three-bedroom lands at roughly $2.45M to $2.77M. That is our own arithmetic on our own range, not a leaked price list. Note what a high land cost does and does not do. It lifts the floor under the price, without guaranteeing the market pays the ceiling.
With any line that has not opened, we ask what holds if it slips. Here the answer is a comfortable one. The North East Line station runs today, and it sits inside the building. So the commute case stands on its own today. The Cross Island Line is upside on top of a working position, not the foundation of one. Not every project currently selling a future line can say that.
Hougang is a mature town, not an area being rebuilt. There is no Tengah or Bidadari scale masterplan here. The estate is fully built out, and the catalyst list is one rail upgrade plus one commercial rebuild. What it does have is scarcity of a specific kind. There has been no new private launch since The Florence Residences in 2019, and no state land plot in the immediate area since 2014. A decade-long supply drought is not a growth story, though. Both things are true at once: the drought is real, and the catalyst list is short.
On our own school dataset, five primary schools fall inside the 1km band. Montfort Junior is about 0.27km away. CHIJ Our Lady of the Nativity is about 0.64km. Holy Innocents’ Primary, a Special Assistance Plan school, is about 0.67km. Punggol Primary is about 0.70km and Yio Chu Kang Primary about 0.92km. Just beyond, Xinmin Primary sits at about 1.00km, and Rosyth School, which runs the Gifted Education Programme, at about 1.92km. These are straight-line distances taken from OneMap map data. MOE measures priority on its own basis, so confirm the current band on MOE SchoolFinder before you rely on it.
It is worth being precise about what that distance buys, because the ballot record answers it. In the 2025 P1 exercise, Holy Innocents’ Primary balloted at Phase 2C. Phase 2C is where children with no sibling or alumni link register. There were 96 citizen applicants living within 1km for 45 places. Distance gets you into the ballot, but not through it.
The contrast inside the same catchment is the more useful lesson. Montfort Junior took 11 Phase 2C applicants against 118 places in the same exercise. So “five schools within 1km” spans everything from heavily oversubscribed to comfortably open. Which school a family is actually aiming at matters far more than the count. Our wider analysis is in primary schools and new launch demand.
Beyond schools, this catchment is complete on day one, rather than on a masterplan. Hougang Mall and Kang Kar Mall are within 300m. Hougang Polyclinic is about 0.44km away and Hougang Sport Centre about 0.49km. Punggol Park, at 16 hectares, is about 0.89km. Ci Yuan and Buangkok hawker centres are a little over a kilometre out. Montfort Secondary, Holy Innocents’ High and Anderson Serangoon Junior College all sit within about a kilometre. In daily terms, what integration buys is less friction. Groceries, clinic, food court, bus and train without stepping outside.
This is the section most launch material skips. Sengkang Grand Residences is the right yardstick. It was completed in 2023, built over Buangkok MRT with a mall beneath. In this corridor it is the closest thing to what Hougang Central will be. On our caveat data it resells at roughly $2,079 psf in 2026 and rents at about $5.64 psf a month. That is a gross yield near 3.3%. The Florence Residences runs a similar 3.5% on a lower entry price. Hougang Central would enter at roughly $2,580–$2,920 psf (est.), while renting into the same north-east tenant pool at broadly the same rents. That puts a starting gross yield closer to 2.4% before costs. It falls again after the higher non-owner-occupied property tax, maintenance and a month of empty weeks.
That is a comment on the yield, not on the project. Here the case is scarcity and the 2030 interchange, not rental income.
What the same data does support is the exit rather than the yield. Across District 19, our matched buy-and-sell records show 17,946 completed exits. 95% of them were profitable, at a median gain of 3.6% a year over a median 8.4-year hold. Sengkang Grand’s own record is 145 matched exits with none at a loss. Median entry was $1,727 psf, against a median exit of $2,032 psf since 2025. Anyone buying mainly for income should run their own entry price through our new launch ROI calculator rather than lean on a corridor average.
Four kinds of buyer fit. Hougang, Sengkang and Serangoon upgraders who want to stay inside their school and family network. They will pay for the station rather than a walk to it. Landed and larger-condo right-sizers around Serangoon Gardens and Jalan Pelikat, trading upkeep for a lift ride to the MRT. Families for whom the 1km band around Holy Innocents’ or CHIJ Our Lady of the Nativity will shape the next decade. And long-horizon buyers who read a two-line interchange plus a trust-owned mall as a durable position rather than a launch feature.
It does not fit the buyer whose whole budget is HDB sale proceeds with nothing on top. Hougang five-room resale medians reported for 2025 sat near $830,000. After the CPF refund and an outstanding loan, a typical flat sale bridges a two-bedroom here, not a three. That gap is real, and no payment schedule dissolves it. Nor does it fit the buyer who wants the widest cushion outside the central region. On land cost alone, Chencharu Close at $980 psf ppr is the honest cheaper option. It deserves a look first.
Standard private condo rules apply. There is no citizenship restriction and no minimum occupation period. Your total monthly loan repayments are capped at 55% of gross monthly income. The test uses a 4% interest rate, not the rate you are offered. You can borrow up to 75% of the price on a first housing loan.
Singapore Citizens pay no Additional Buyer’s Stamp Duty on a first property, 20% on a second and 30% on a third or later. Permanent Residents pay 5% on a first and 30% on a second. Foreign buyers pay 60%. Buyer’s Stamp Duty runs on the tiered scale, about $93,100 on a $2.47M purchase.
Seller’s Stamp Duty is the tax for selling too soon after buying. Under the schedule effective 4 July 2025 it runs at 16%, 12%, 8% and 4% across four years. The clock starts when the option is exercised, not when you get the keys. On a Q2 2027 preview and a 2031 to 2032 completion, a purchase here would normally be clear of it before the keys arrive.
Progressive payments soften the cash profile. You pay 5% on booking in cash, then 15% plus Buyer’s Stamp Duty at exercise about three weeks later. After that, payments are staged against construction milestones, with 25% at completion and the balance a year on. Maintenance and property tax start when the building is finished, not when you book. On a build this long, that distinction is worth holding onto.
Before preview, the concrete step is an in-principle approval from a bank, so you know which unit types you can afford instead of guessing. Work the numbers through our affordability calculator, stamp duty calculator and progressive payment calculator. Upgraders selling a flat first should start with selling an HDB to buy a new launch. The borrowing mechanics are set out in our TDSR guide. Test the repayment above today’s package rates rather than at them. We do not forecast rates, and neither should a purchase decision.
The risks worth pricing in are below. Each comes with the context that softens or sharpens it.
The trade is simple once stated as a trade. You pay what is likely to be a Hougang record, an indicative $2,580–$2,920 psf (est.), against a local resale band of roughly $1,760–$2,079 psf. In exchange you get a home physically above a working MRT station, and a two-line interchange with a funded 2030 date. You also get a bus interchange rebuilt into the building. And a 300,000 sq ft mall owned by a trust for good, rather than sold off unit by unit. And first-mover position in a town with no new private supply since 2019. That suits an upgrader or right-sizer with room above the median flat-sale bridge, on a long view, buying the position rather than the price. It does not suit a buyer stretching to the last dollar. Nor one buying mainly for rent at roughly 2.4% gross (est.). Nor one who would rather have the cushion, which at $980 psf ppr land cost is Chencharu Close’s argument, not this site’s.
Two numbers will do the deciding. The first is the launch price against our $2,580–$2,920 indicative range. If it prints nearer the analyst view of $2,500–$2,600, the developer is absorbing part of the record land cost rather than passing it on. The value case improves materially in that case. The second is how many units sell on day one, which tells you whether 835 units at a Hougang record is depth or overhang. We revisit both once the developer publishes a price list.
Wider context sits in our GLS pipeline tracker, our land cost comparison and the price trends dashboard. The nearest District 19 option is examined in the Chuan Grove GLS investment analysis. Interested buyers should visit the Hougang Central Residences appointed developer sales website to register for the preview, get the latest e-brochure and book a showflat viewing. Floor plans appear there as the developer confirms them. Use this page as the yardstick to judge them against.
So what should you do with this? If cheap land is what you are after, price Chencharu Close at $980 psf ppr before you price this one. If the station is what you want, work out what your flat nets after the CPF refund and outstanding loan. Then check it against a two-bedroom here rather than a three. And when the price list lands, see whether it prints nearer $2,500 or nearer $2,920. That tells you who is carrying the record land cost.
Sources: HDB conditions of tender for Hougang Avenue 10 / Hougang Central (29 May 2025) and the 14 January 2026 award; URA and HDB government land sale records compiled in our own land cost tracker; LTA Cross Island Line Phase 1 records; CapitaLand, UOL and CICT public statements; MOE school data and 2025 P1 balloting releases compiled in our own schools dataset; URA caveat data compiled by PropertyInsider.sg for resale, rental and matched-exit figures; OneMap (SLA) geocodes; IRAS and MAS for stamp duty, LTV and TDSR rules. Figures marked (est.) are our estimates and subject to change at preview; no price list exists for this project. Past performance of comparable projects is not indicative of future results. This page is research, not financial advice. PropertyInsider.sg is an independent research publication and does not take developer fees for its research. The publisher’s agency is part of the developer’s appointed sales team for this project; that work sits outside the research desk and does not change our figures or verdict. See our editorial policy.
Preview is targeted for Q2 2027 (est.), and the developer has not confirmed a date. The project name, unit mix and site plan are expected earlier, around the second half of 2026 to Q1 2027. Estimated completion is 2031 to 2032.
No price list exists yet. Our indicative range is $2,580–$2,920 psf. It comes from an estimated breakeven of about $2,247 psf ppr, and the 1.15–1.30 margin band we apply to every project on this site. Analyst commentary at the January 2026 award pointed slightly lower, at roughly $2,500–$2,600 psf. Both are estimates, and the developer has confirmed neither.
It is the highest rate ever paid for a mixed-use state site outside the central region. That sets the floor under the launch price. Our breakeven alone is about $2,247 psf ppr. It deserves context, though. Two Chuan Grove plots in the same district were awarded at $1,331 and $1,376 psf ppr in 2025, as plain housing sites. So this is a record for its type of site, not for District 19.
About 835 private homes above roughly 300,000 sq ft of lettable retail, owned by CapitaLand Integrated Commercial Trust. A rebuilt bus interchange of at least 6,500 sqm comes with it, joined to Hougang MRT as one transport hub. The housing joint venture is CapitaLand Development, UOL Group, Singapore Land Group and Kheng Leong.
On our dataset, five sit inside the 1km band, measured in a straight line from OneMap map data. They are Montfort Junior (~0.27km) and CHIJ Our Lady of the Nativity (~0.64km). Then Holy Innocents’ Primary (~0.67km), Punggol Primary (~0.70km) and Yio Chu Kang Primary (~0.92km). MOE measures on its own basis, so confirm via MOE SchoolFinder. Being inside the band earns a place in the ballot, not a place at the school. Holy Innocents’ balloted at Phase 2C in 2025 with 96 within-1km citizen applicants for 45 places.
The existing Hougang Bus Interchange. It is being rebuilt inside the new scheme rather than moved elsewhere. This is Hougang’s first state housing site in over a decade. The last nearby award was the Stars of Kovan site in 2014. The town’s last new private launch was The Florence Residences in 2019.
Probably not as the main case. At our indicative range the starting gross yield works out near 2.4% before costs. That compares with about 3.3% at Sengkang Grand Residences, the nearest station-linked comparison, on our own caveat and rental data. The stronger evidence is on exit rather than income. Across District 19 our matched records show 17,946 completed exits, 95% profitable, at a median 3.6% a year over a median 8.4-year hold.
Seller’s Stamp Duty runs at 16%, 12%, 8% and 4% across four years. The clock starts when the option is exercised, not when you get the keys. Take a purchase previewing in 2027, with completion estimated at 2031 to 2032. A five-year hold would normally be clear of it before the keys are handed over. Confirm current rates with IRAS before committing.
What a loan of this size costs a month, before you talk to a bank. Change any figure — the instalment, the loan amount and the interest bill all recalculate as you type.
The split shown is the first month’s instalment, not an average: early payments are mostly interest and late ones mostly principal, while the monthly figure itself stays level. This is the loan only — it excludes stamp duty, legal fees, maintenance and property tax, and a home bought under construction draws the loan down in stages rather than all at once. What a bank will actually lend you depends on the LTV limit, TDSR and, for HDB flats and developer-sold ECs, MSR. Work those out on the affordability calculator, stamp duty calculator and progressive payment calculator. Estimates only, not financial advice.
The analysis on this page tells you what the data says. If you want to work through what it means for your own situation — budget, ABSD position, timing an HDB sale, or how this project compares with alternatives — you can request a one-to-one consultation.
Disclosure: advisory consultations are provided by Jamus Lee (CEA Reg. No. R065771E, ERA Realty Network Pte Ltd, Licence No. L3002382K), the publisher of PropertyInsider.sg, via JamusProperty.com. This is a separate service from our editorial research and has no influence over what we publish. See our editorial policy. Submitting this form shares your details with the advisory practice; see our privacy policy.