Hillock Green
5 units available
$2,115–$2,262 psf
99% sold
Upper Thomson (Parcel A) GLS is an upcoming launch in D26 (OCR, North region) — GLS site: Upper Thomson (Parcel A). Everything below is compiled from matched transactions, URA tender data and public sources.
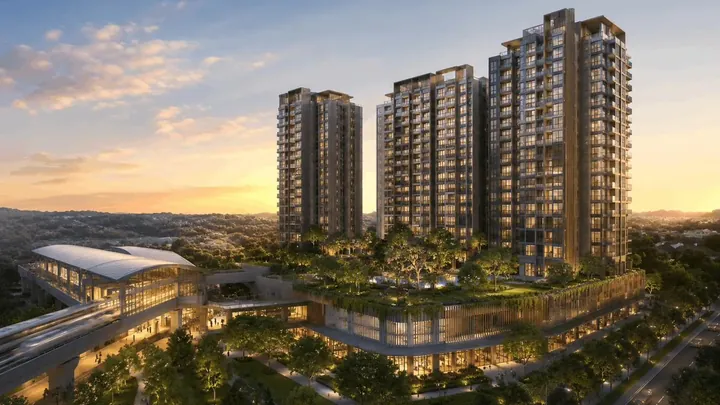
Artist impressions and marketing images are supplied by the developer and compiled by PropertyInsider.sg. They are indicative only, may show upgraded finishes or landscaping that is not part of the standard specification, and are not a representation of the completed development. Verify the specification against the developer’s sales documents.
Upper Thomson (Parcel A) GLS is an upcoming 595-unit 99-year leasehold condominium in D26 (OCR, North region), developed by Wee Hur Holdings, with completion expected in 2031.
The site sits about 0.13 km in a straight line from Springleaf (TE4), roughly 2 minutes on foot. It has not launched. Our estimated launch range is $2,400–$2,710 psf (est.), anchored on an estimated breakeven of $2,085 psf ppr — see the estimate and its cost stack below.
This overview is generated from PropertyInsider.sg’s tracked record for this project — URA tender data, matched caveat transactions and public filings — not from developer marketing material. Figures as at 20 Oct 2026. Anything marked (est.) is our estimate and is explained where it appears.
The full tracked record for Upper Thomson (Parcel A) GLS, grouped by what it tells you. Every figure here is repeated in context further down the page, with its source and its caveats.
Compiled by PropertyInsider.sg from URA tender records, matched caveat transactions and public filings; last refreshed 20 Oct 2026. Values marked (est.) are our estimates — the launch-price method is set out in our pricing methodology.
PropertyInsider’s estimated launch price for this site, and the indicative quantum that range implies at typical unit sizes.
Breakeven is the estimated total development cost divided by gross floor area, in dollars per square foot per plot ratio — the same basis as the land rate. Cost stack: PropertyInsider.sg cost model, land awarded 31 Oct 2025. Figures are estimates (est.), not the developer’s accounts.
Estimates are anchored on the site's estimated breakeven rate and a measured developer margin band; developers make final pricing decisions. Indicative quantums apply the estimated psf range to typical unit sizes — not a price list.
Where Upper Thomson (Parcel A) GLS sits on the map, with its district, market segment and nearest station on the rail network. The nearest MRT station is Springleaf (TE4), about 0.13 km away in a straight line, roughly 2 minutes on foot. The dashed rings on the map mark straight-line 1 km and 2 km radii from the site.
Upper Thomson (Parcel A) GLS is located at 1.39744, 103.81721 in D26, Singapore. The interactive map loads when this section comes into view.
Open this location in Google Maps·Every tracked launch on one map·Primary schools map
The marker is an approximate site centroid compiled by PropertyInsider.sg, not a surveyed boundary. Station distances are straight-line, measured from the site centroid to the midpoint of a station’s published exits (LTA MRT/LRT exits dataset) — not the distance to the nearest exit, and not a walking route. Walking times are an estimate only and are omitted beyond 2 km. Base map tiles are © OneMap / Singapore Land Authority. Verify exact addresses, boundaries and journey times with the developer or on OneMap.
The places that actually shape how this address lives day to day — stations, schools, food, shops, green space, healthcare and the nearest employment nodes — with a straight-line distance and an estimated walk and drive for each. Use the buttons below to hide a category on the map above and in this table at the same time.
| Place | Straight line | On foot | By car |
|---|---|---|---|
| Springleaf MRTTE4 · Thomson-East Coast Line | 0.13 km | 2 min | — |
| Springleaf Nature ParkPark · 18 ha | 0.60 km | 9 min | — |
| Upper Seletar Reservoir ParkPark · 13 ha | 1.17 km | 17 min | 3 min |
| Thomson Nature ParkPark · 51 ha | 1.73 km | 26 min | 5 min |
| Yishun Sport CentreActiveSG sport centre nearest — beyond 2 km | 2.24 km | — | 6 min |
| Lentor ModernShopping mall nearest — beyond 2 km | 2.33 km | — | 7 min |
| Peiying Primary SchoolModerate P1 demand nearest — beyond 2 km | 2.65 km | — | 8 min |
| Naval Base Secondary SchoolSecondary nearest — beyond 2 km | 2.88 km | — | 8 min |
| Ang Mo Kio - Thye Hua Kwan HospitalGovernment-funded community hospital nearest — beyond 2.5 km | 2.96 km | — | 9 min |
| Jalan Leban Food CentreHawker centre · 36 cooked-food stalls nearest — beyond 2 km | 3.09 km | — | 9 min |
| Sir Manasseh Meyer International SchoolInternational school nearest — beyond 3 km | 4.44 km | — | 13 min |
| Seletar Aerospace ParkBusiness and innovation park | 5–10 km | — | 20–30 min |
| Woodlands Regional CentreRegional commercial centre | 5–10 km | — | 20–30 min |
| DigiPen Institute of Technology SingaporeOverseas university partner nearest — beyond 3 km | 6.40 km | — | 19 min |
| Downtown (CBD and Marina Bay)Central business district | 10–15 km | — | 30–45 min |
No categories selected. Pick one above, or .
15 places shown Every distance here is a straight line between two points, not a walking or driving route, and each place is a single representative coordinate — a park or a business district is one point, not its nearest entrance. Treat them as a ranking of what is close, not as journey times. Verify anything you are relying on with OneMap. Primary-school bands carry their own MOE caveat in the schools section below.
Distances are straight lines from an approximate site centroid compiled by PropertyInsider.sg, not walking or driving routes, and each place is a single representative coordinate. Walking times are an estimate only, at an 80 m/min pace with a 1.2× allowance for street routing, and are omitted beyond 2 km. Verify anything you are relying on with OneMap.
Matched developer-sale transactions by bedroom type: average price, average psf, transacted price range, size range and units sold. Entry prices usually reflect lower floors or less ideal facings.
| Type | Avg price | Avg psf | Transacted range | Size range | Units sold | Available |
|---|
Site plans are developer marketing material compiled by PropertyInsider.sg. Block positions, unit counts, facing and facility placement are indicative and can change between the marketing plan and the approved building plan. Confirm against the developer’s sales documents and the approved plans before relying on a stack, facing or distance.
| Date | Unit | Type | Size | Price | Price psf |
|---|
Capital appreciation context for Upper Thomson (Parcel A) GLS: what sellers of completed condos in the same district actually realised on 1,824 matched buy-and-sell pairs (March 1995 to October 2026), including the 26.0% that sold at a loss.
Quarterly median exit psf of all matched resales, profitable and not, March 1995 to October 2026. Quarters with fewer than 5 exits carry no point; lines bridge to the next qualifying quarter. Source: URA caveat data, matched pairs.
Completed condos in D26 with at least 20 matched exits — the closest historical read on what this location has delivered. Ranked by median annualised return across every exit, not only the profitable ones.
Map of the 5 projects ranked below. Each pin is labelled with that project’s median annualised return.
| Project | TOP | Exits | Profitable | Median ann. return | Median hold | Median gain | Avg psf |
|---|---|---|---|---|---|---|---|
| Lentor Modern | 2025 | 62 | 98.4% | 4.5% p.a. | 3.6y | $338k | $2,125 |
| Meadows @ Peirce | 2012 | 293 | 99.3% | 3.8% p.a. | 8.1y | $361k | $1,044 |
| Bullion Park | 1993 | 268 | 76.9% | 2.3% p.a. | 12.0y | $232k | $1,734 |
| Castle Green | 1997 | 568 | 76.2% | 1.8% p.a. | 12.3y | $201k | $1,898 |
| Seasons Park | 1997 | 610 | 55.1% | 0.5% p.a. | 13.2y | $33k | $1,482 |
Projects in the same district with at least 20 matched exits, ranked by median annualised return across every exit — profitable and not. Median gain is gross, before stamp duties, legal and agent fees, mortgage interest and renovation. Realised outcomes of past projects are context, not a prediction for this launch. Full dataset: resale exit dashboard.
What the developer paid for this site, ranked against the sites most like it — same market segment and planning region where we have enough of them, widening only if we do not. Land is the largest single input into a launch price and it is fixed two to three years before the show flat opens. Every tracked site sits on the land cost tracker.
MOE primary schools within a straight-line 1km and 2km of this project, with each school's P1 demand tier and phase-by-phase oversubscription ratios from the last completed registration exercise. An address inside a school's 1km band ranks highest whenever that school ballots. Explore every school on the primary schools map.
Phase chips show applicants per place: 1.00× or under every applicant placed, 1.01–1.50× oversubscribed, above 1.50× heavily oversubscribed. Distances are straight-line estimates computed from project and school coordinates and shown to 2 decimal places — they are not the official home-school distance. Walking times use the same model as the nearby-places table above: 80 m/min with a 1.2× allowance for street routing, omitted beyond 2 km. For P1 registration, verify the exact 1km/2km status with the OneMap School Query tool, which applies MOE’s official measurement. No guarantee of accuracy; school demand tiers reflect the 2026 P1 exercise and can change year to year. The tier is read from Phase 2C alone — the round for children with no family link to the school, and the only one where home distance decides who gets in. Very high demand means the 2C ballot cut into citizens within 1km AND at least 1.5 applicants turned up per place. Full map and methodology: primary schools near new launches.
Other tracked launches and GLS sites in D26 or the same segment and region.
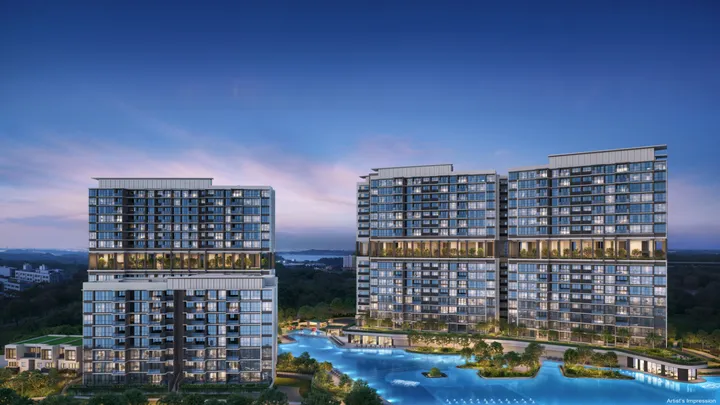
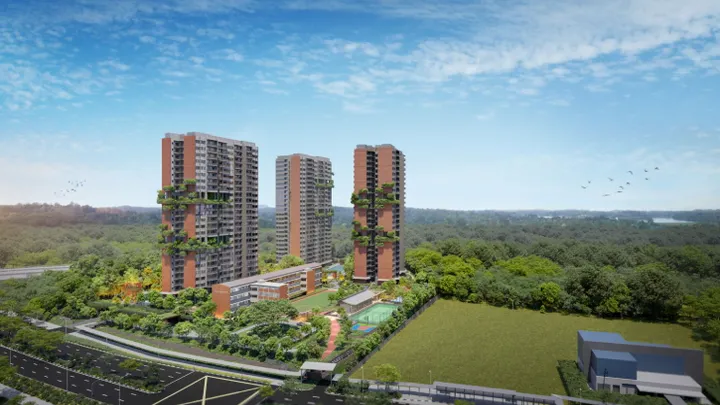
Upper Thomson (Parcel A) GLS is a planned scheme of about 595 units on Upper Thomson Road, in the Springleaf pocket of District 26. The lease is 99 years. The developers are a joint venture between Wee Hur Property and GSC Holdings. The state land site was awarded at $613.9 million, or $1,062 psf ppr, at the end of October 2025. Preview is tracked for Q1 2027 (est.), with completion around 2031 (est.).
Two facts define the site, and they pull against each other. The first is genuinely uncommon. The scheme takes in the existing Springleaf MRT (TE4) station entrance. The train is built into the block, not a walk across the estate. Our own data puts the station 0.13km away. The second is a confirmed constraint, not a gap in what we know. On our schools dataset the nearest MOE primary school is 2.65km away. So nothing falls inside the 1km or the 2km registration band. This is also the second high-rise plot in the pocket rather than the first, so it launches with a benchmark next door instead of into a vacuum.
The station and the reservoirs are the easy sell. The sums are the rest of it. What must the developer charge to clear its costs? Does that number ask buyers to pay more than the only evidence the pocket has? And what does a buyer give up in exchange for the station? Every figure below is either a tender fact, a policy fact, or a labelled estimate.
The land number carries a story, and the story explains the number. Parcel A was offered once before and failed to sell. The gap between the two tenders is the clearest before-and-after read on Springleaf demand that exists anywhere.
Read it practically. A plot that attracted nobody in December 2023 attracted five bidders inside two years. The top bids clustered within 2% of each other. A wide spread would suggest one developer talking itself into a number. A 2% spread across five bidders is the market agreeing on what Springleaf land is worth. That is reassuring about demand. It is unhelpful for anyone hoping the winner overpaid and will be forced to launch cheap. By contrast, the Lentor Gardens site down the corridor drew only two bids in April 2025.
The land rate is the one fixed number, so any honest estimate starts there. At $1,062 psf ppr, Parcel A cost 17% more than the sister plot that became Springleaf Residence, and 15% more than Lentor Gardens. But it is not the corridor’s high point. Any page still saying so is working off 2025 data. Lentor Central (Plot 4) was awarded at $1,278 psf ppr in March 2026, 20% above this site. The table sets the awards out with their estimated breakevens, which is the comparison that actually matters to a buyer.
| Site (project) | Awarded | Land psf ppr | Est. breakeven | vs Parcel A |
|---|---|---|---|---|
| Upper Thomson Rd Parcel B (Springleaf Residence) | Apr 2024 | $905 | $1,688 | −15% |
| Lentor Gardens (Lentor Gardens Residences) | Apr 2025 | $920 | $1,894 | −13% |
| Lentor Central (Lentor Central Residences) | Sep 2023 | $982 | $1,793 | −8% |
| Upper Thomson Rd Parcel A (this site) | Oct 2025 | $1,062 | $2,086 | Baseline |
| Lentor Central (Hillock Green) | Sep 2022 | $1,108 | $1,963 | +4% |
| Lentor Hills Rd Parcel B (Lentoria) | Sep 2022 | $1,130 | $1,993 | +6% |
| Lentor Central (Lentor Modern) | Jul 2021 | $1,204 | $1,933 | +13% |
| Lentor Central Plot 4 (GLS, unnamed) | Mar 2026 | $1,278 | $2,378 | +20% |
Land is one line in the stack. The site has 53,729 sqm of buildable floor area, or about 578,000 sqft. Spread our cost estimate across that and you get roughly $1,062 psf of land and $546 of construction. Then $192 of professional fees, $167 of finance and $118 of marketing. The estimated breakeven comes to near $2,085 psf ppr. Applying the 1.15–1.30 margin band we use on every project on this site gives an indicative launch range of $2,400–$2,710 psf. The full working is in our pricing methodology, and the corridor comparison sits in the land cost tracker. Note the construction line. At $546 psf it is the heaviest in the corridor table. That fits a site carrying green-design rules and an MRT structure to build around. The developer had that cost in its bid, not added afterwards.
One further read from the floor area. Take out the required shop and childcare space and roughly 551,000 sqft of housing is left, across about 595 units. That implies an average near 925 sqft per unit (est.), which is a mainstream family mix rather than a shoebox-heavy one. That is our inference from the tender record, not something the developer has disclosed. The actual mix is only known at preview.
Most launch transport claims depend on something being finished later, but this one does not.
With anything not yet built, we ask what holds if it slips. Here the answer is comfortable. The working Thomson-East Coast Line station carries the whole commute case on its own. The RTS link and the North-South Corridor, targeted for phased completion around 2027, are upside on top of a case that already stands. That is the opposite shape from most launches outside the central region, where the transport argument is a promise with a date on it.
That is a short list, and none of it is a new-town masterplan. Springleaf is a small, low-rise, largely landed pocket. It is getting two condos and a supermarket, not a Tengah or a Bidadari. What exists today is a row of shophouses opposite the site. Springleaf is not being transformed. It is being filled in. The accurate framing is narrower and easier to defend. This is a quiet green address with a working MRT station attached, whose shops are forming rather than formed.
This is the site’s hardest constraint, and it deserves a straight answer. On our own schools dataset, measured straight-line from OneMap map data, the nearest MOE primary school is Peiying Primary at about 2.65km. Anderson Primary sits at about 3.03km, and CHIJ St. Nicholas Girls’ at about 3.25km. Nothing sits inside 1km, and nothing sits inside 2km. MOE measures priority on its own basis, so confirm the position on MOE SchoolFinder before you rely on it. But this is a confirmed absence rather than a data gap. No future information is going to move a school 1.7km closer.
What that costs a family is less than the headline suggests, and it is worth being precise about why. Distance matters most where a school is oversubscribed. On the 2025 registration record in our dataset, Peiying, the nearest school, did not ballot at Phase 2C at all. Phase 2C is the round left for families with no existing tie to the school. It had 105 places against 53 applicants. Anderson did ballot at 2C, with 91 applicants for 65 places. So did CHIJ St. Nicholas, with 71 for 41.
So a family here sits outside the 1km band for schools that, in the nearest case, are not fighting for places at all. Being inside the band gets a family into a ballot. It does not win one. And here there is often no ballot to enter. What is genuinely lost is the daily convenience of a school within walking distance, plus any within-1km advantage at the two busier schools. Our wider analysis is in primary schools and new launch demand.
On everyday life, the required on-site supermarket, shops and childcare centre will change the local offering a great deal. Today it is the Upper Thomson shophouse row and little else. Thomson Plaza, Junction 8 and the Sembawang and Yishun town centres are all drives rather than walks. The reservoirs, Springleaf Nature Park and the Central Catchment trails are the compensation. For a certain buyer they are the whole point.
There is no rental evidence for this pocket. We would rather say that than manufacture a yield figure. Springleaf Residence, the only comparison, does not complete until 2029. So the corridor has no letting history at all, and no live rental figure to work from. Anyone quoting a Springleaf yield today is borrowing it from elsewhere without saying so.
What can be said is structural. The tenant demand arguments here are threefold. The Woodlands Regional Centre jobs two stops away. Cross-border commuters once the RTS runs. And spillover as the Lentor cluster finishes and recycles tenants. Those make a rental market plausible. They do not make it rich. At an estimated $2,400–$2,710 psf entry, the starting yield will almost certainly disappoint. The same money buys more rent in a finished, established corridor. The case doing the work at this site is capital growth and the station, not income. An investor who needs the rent to carry the holding cost should model it in our new launch ROI calculator before committing, not after. For evidence on how District 26 exits have actually behaved, our study of Lentor Modern sub-sale profits is the nearest real-money read.
The clearest fit is the District 26 upgrader or right-sizer. They value a direct Thomson-East Coast Line commute and green, low-rise surroundings above being near a school. Think of an Ang Mo Kio, Bishan, Yishun or Woodlands flat owner past their five-year minimum stay. They have real cash behind them, and they are buying a home rather than a trade.
A second group is local. Upper Thomson, Mandai and Sembawang Roads carry established landed estates. The right-sizer cashing out of a high-upkeep landed house into a lock-and-go condo in the same neighbourhood is a genuine, if quiet, pool. So are the grown children of those households. The third group is the buyer who simply wants the station, and for whom an entrance in the block is worth paying for.
It does not suit a family for whom a primary school inside 1km is the deciding factor. A Lentor address does that job, and we would rather say so than talk around a 2.65km gap. It also does not suit a buyer stretching to the last dollar on the assumption of a quick repricing. The pocket’s own evidence from a finished building does not arrive until 2029.
As a private condo there are no citizenship or income ceilings. The duty and lending rules do the sorting instead.
Additional Buyer’s Stamp Duty, as at this update, is 0% for a Singapore Citizen’s first property. It is 20% on a second and 30% on a third or more. Permanent Residents pay 5%, 30% and 35%. Foreign buyers pay 60%, and companies 65%. You can borrow up to 75% of the price on a first housing loan. That drops to 55% where the loan runs past age 65 or beyond 30 years. Your total monthly loan repayments are capped at 55% of gross income. The test uses a 4% floor rate, not the rate you are offered. Buyer’s Stamp Duty runs on the IRAS scale, and is due within 14 days of exercising the option.
Seller’s Stamp Duty is the tax for selling too soon after buying. For anything bought on or after 4 July 2025 it runs four years, at 16%, 12%, 8% and 4%. The clock starts when the option is exercised, not when you get the keys. On a building still under construction, that is the difference between clearing it near completion and clearing it years later.
Because the building is not yet built, payment follows the standard staged schedule. You pay 5% cash on booking, then 15% plus Buyer’s Stamp Duty within about three weeks at exercise. After that, instalments are drawn from the loan as construction stages complete. So the monthly outlay before completion is interest on what has been drawn, not a full repayment.
Run the actual numbers on our affordability calculator, stamp duty calculator and progressive payment calculator. Upgraders selling a flat should read selling an HDB to buy a new launch and the TDSR guide first. The order of sale and purchase drives both the stamp duty position and the deposit. The sensible step before any preview is an in-principle approval, and a repayment tested above today’s rate. We do not forecast rates.
Every launch story deserves its counter-case. These are the trade-offs we would weigh, each with the context that sharpens or softens it.
Stated as a trade, it reads like this. You pay an estimated 10% to 24% above what the same pocket sold for eighteen months earlier. In exchange you get a station entrance built into the block and a fresh 99-year lease. You also get the newest stock in a pocket with only two high-rise sites. And a required shop and childcare base that does not exist there today. What you give up is any school inside the registration band. Also a formed local amenity base, and any evidence from a finished building before 2029. That suits the District 26 upgrader or landed right-sizer, on a seven to ten year view. They genuinely value the commute and the green setting. It does not suit a school-driven family, or an investor led by rental yield.
Two numbers will resolve this. The first is the launch price against our $2,400–$2,710 range. Near the bottom, the developer has passed some of the five-bidder discipline to the buyer. At or above the top, where Springleaf Residence’s own realised 1.29 times breakeven points, the buyer is funding the full margin. The second is how many units sell on day one, measured against Springleaf Residence’s near-complete sell-through. That tells you whether the pocket’s demand stretches to a higher price, or was specific to a lower one. We re-check both against the published price list the day it lands.
Wider context sits in our GLS pipeline tracker and our new launch versus resale case studies. Two appointed developer sales websites serve this project: Springleaf Central and Upper Thomson Residence. Interested buyers can use either to register interest, get the latest e-brochure and book a showflat viewing, and both post the preview timeline, unit mix and floor plans as the developer confirms them. Use this page as the yardstick to measure them against.
So what should you do with this? If a school inside 1km matters to your family, stop here and look at Lentor instead. No amount of new information will close a 2.65km gap. If the station is what draws you, note what Springleaf Residence next door achieved. It sold at 1.29 times its breakeven, which points at the top of our range rather than the bottom. So when the price list lands, check it against $2,178 psf rather than against our range alone.
Sources: URA Government Land Sales tender results and quarterly price index releases; development cost stacks and breakeven estimates from the PropertyInsider.sg cost model, applied to our own land-sale register; Wee Hur Holdings SGX disclosures (Mar 2026); LTA network records; MOE school data and P1 registration releases compiled in our own schools dataset; IRAS and MAS for duty, LTV and TDSR rules; our matched caveat dataset for Springleaf Residence and the Lentor corridor. Figures marked (est.) are our estimates and subject to change at preview; indicative launch pricing is produced by our own model and is not developer-confirmed. Past performance of comparable projects is not indicative of future results. This page is research, not financial advice. PropertyInsider.sg is an independent research publication and does not take developer fees for its research. The publisher’s agency is part of the developer’s appointed sales team for this project; that work sits outside the research desk and does not change our figures or verdict. See our editorial policy.
We track preview for Q1 2027 (est.). Wee Hur published its own guidance with its FY2025 results in March 2026. It points to a launch in the first half of 2027, and completion by the first half of 2031. Neither is a developer-confirmed sale date. The unit mix, floor plans and price list are only released at preview.
No price list exists. Our indicative range is $2,400 to $2,710 psf. It comes from an estimated breakeven of about $2,085 psf ppr, and the 1.15–1.30 margin band we apply to every project on this site. On that basis a 650 sqft two-bedroom would sit near $1.56M to $1.76M. A 1,000 sqft three-bedroom would sit near $2.40M to $2.71M. All of these are estimates, and the developer has confirmed none of them.
Land is the largest single line in a developer’s cost stack, so it sets the floor under the launch price. At $1,062 psf ppr this site cost 15% to 17% more than the two District 26 sites awarded before it. That thins the buyer’s cushion. It is no longer the corridor’s highest, though. Lentor Central Plot 4 was awarded at $1,278 psf ppr in March 2026.
No. On our schools dataset, measured straight-line from OneMap map data, the nearest MOE primary school is Peiying Primary at about 2.65km. Anderson Primary follows at 3.03km and CHIJ St. Nicholas Girls’ at 3.25km. Nothing falls inside the 1km or 2km bands. MOE measures on its own basis, so check on MOE SchoolFinder. But this is a confirmed absence, not missing information.
Springleaf Residence, on the next plot, is the only comparison in the same pocket. It has sold about 98% of its 940 units at an average near $2,178 psf. That is roughly 1.29 times its own estimated breakeven. Our $2,400 to $2,710 estimate for Parcel A is around 10% to 24% above that average. Springleaf Residence does not complete until 2029, so there is no resale market in the pocket yet.
The entry price sits above the only evidence the pocket has produced. And no data from a finished building, or from resale, exists until 2029. Second to that, no primary school falls within 2.65km, which narrows the family-buyer pool. Today’s local amenity is a shophouse row rather than a town centre.
A joint venture between Wee Hur Property and GSC Holdings. GSC is Wee Hur’s own controlling shareholder rather than an outside partner. So the money and the delivery sit on the same side of the table. Wee Hur is the property arm of an SGX-listed builder-developer founded in 1980. Its recent Singapore projects, including Bartley Vue and Parc Botannia, sold out.
The scheme is required to take in the existing Springleaf MRT (TE4) station entrance and exit. So the station connects into the building rather than sitting a walk away across the estate. Our data places the station 0.13km from the site. TE4 runs today. It reaches Orchard, the CBD and Marina Bay on the Thomson-East Coast Line with no change.
What a loan of this size costs a month, before you talk to a bank. Change any figure — the instalment, the loan amount and the interest bill all recalculate as you type.
The split shown is the first month’s instalment, not an average: early payments are mostly interest and late ones mostly principal, while the monthly figure itself stays level. This is the loan only — it excludes stamp duty, legal fees, maintenance and property tax, and a home bought under construction draws the loan down in stages rather than all at once. What a bank will actually lend you depends on the LTV limit, TDSR and, for HDB flats and developer-sold ECs, MSR. Work those out on the affordability calculator, stamp duty calculator and progressive payment calculator. Estimates only, not financial advice.
The analysis on this page tells you what the data says. If you want to work through what it means for your own situation — budget, ABSD position, timing an HDB sale, or how this project compares with alternatives — you can request a one-to-one consultation.
Disclosure: advisory consultations are provided by Jamus Lee (CEA Reg. No. R065771E, ERA Realty Network Pte Ltd, Licence No. L3002382K), the publisher of PropertyInsider.sg, via JamusProperty.com. This is a separate service from our editorial research and has no influence over what we publish. See our editorial policy. Submitting this form shares your details with the advisory practice; see our privacy policy.