The strongest signal from the third quarter is not a price index. It is what developers paid for land. Sites sold in 2026 at record rates will launch in 2027, and our own cost model says most of them cannot price much below $2,900 psf. That makes today's launches, priced off older and cheaper land, the reference point. It does not make every purchase urgent.
On 29 October, Marcus Chu and Eugene Lim walked through the quarter's numbers and closed with a clear call: the weeks before year-end are a window, so get in before the next step up in prices. I agree with the first half. The land argument is the most solid thing in the deck, and our own estimates back it. The second half needs sorting by buyer, because the window differs for a first-timer, an EC buyer and an upgrader. Three weeks on, part of it has already closed.
Five terms used in this article
- psfPer square foot. A home's price divided by its floor area, so homes of different sizes can be compared
- psf pprWhat a developer paid for land per square foot of floor area it may build. The starting cost of every future flat
- CCR / RCR / OCRCore Central Region (the prime districts), Rest of Central Region (the ring around them) and Outside Central Region (the mass-market estates). URA's three segments
- MOPMinimum Occupation Period. How long you must live in an HDB flat or EC before you can sell it
- ECExecutive condominium. A condo sold with HDB rules and an income ceiling, which becomes fully private later
What did the third-quarter numbers show?
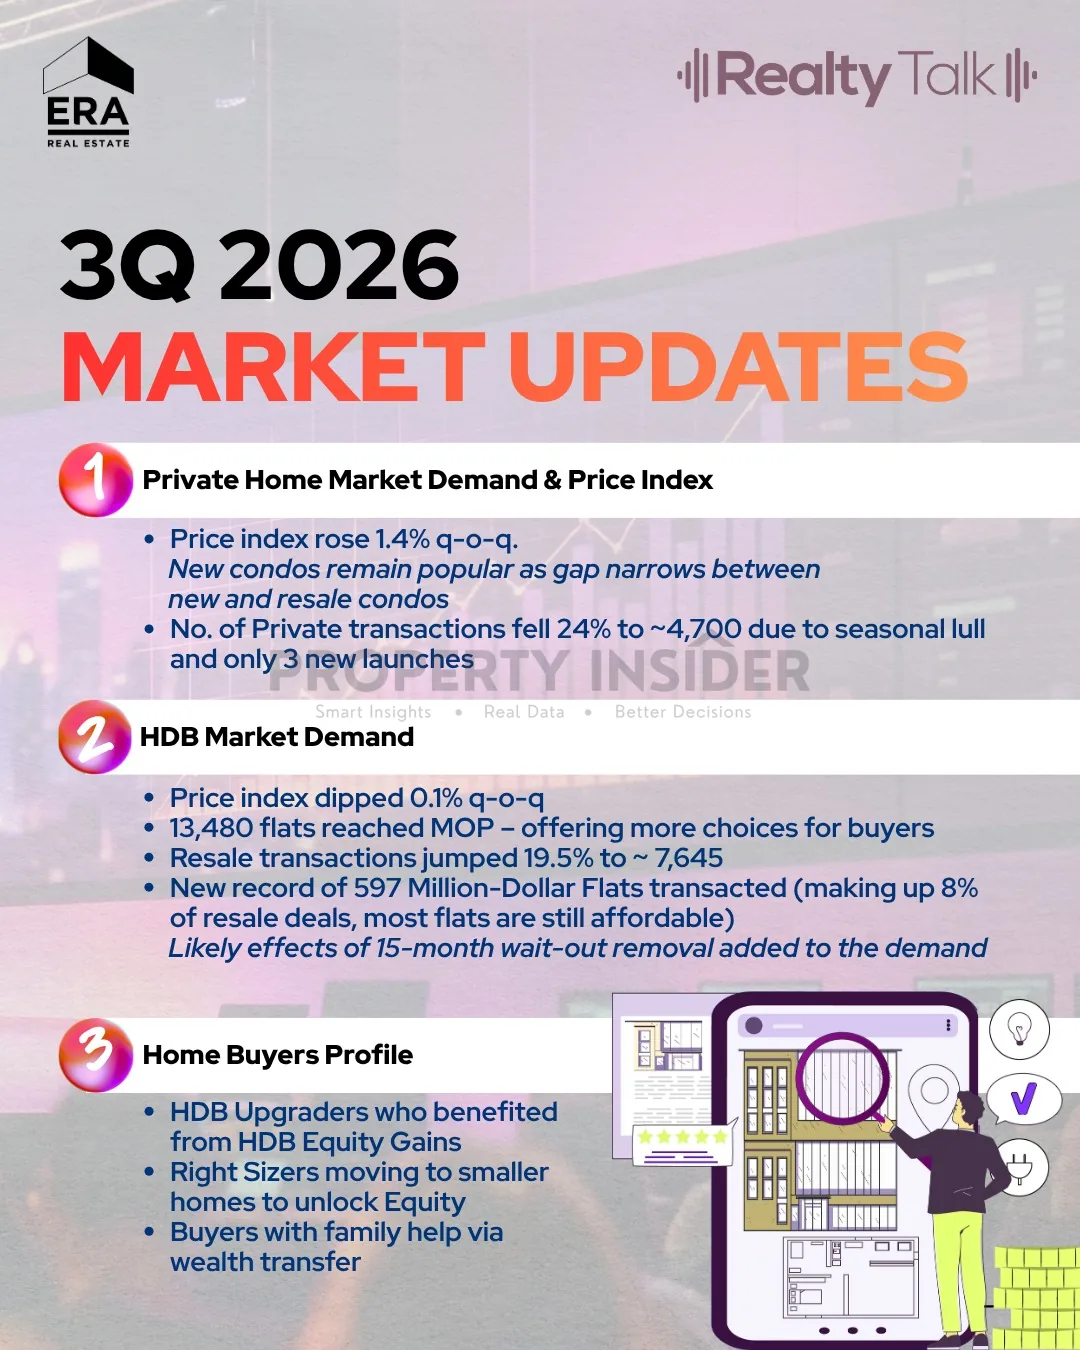
Private prices rose faster while fewer homes changed hands. URA's price index went up 1.4% in the third quarter, against 0.5% in the second. ERA called it the fastest quarterly rise in almost two years. Landed homes did most of the lifting, up 2.8%. Condos rose 0.9%, and condos in the prime CCR districts slipped 0.1%.
Volume went the other way. ERA counted about 4,700 private deals, down 24% from about 6,100. Developers sold only 1,183 new homes, against 2,141 the quarter before, on URA's count. There were just three launches, because developers avoid the Lunar seventh month. So prices rose on thin trading, carried by landed homes. That is a weaker signal than the headline suggests.
The gap between new and resale condos kept closing. For January to October 2026, ERA put the median new-sale price at $2,548 psf and the median resale price at $1,776 psf. That is a gap of $772 psf, down from a peak of $908 psf. When the extra cost of a new home shrinks, a fresh 99-year lease and a modern layout get easier to justify. Our new launch vs resale guide works through that trade in full.
Why are more HDB flats selling while prices stay flat?
Because more buyers arrived, but they bought the bigger flats and stopped short of chasing price. HDB's final figures show 7,645 resale deals in the quarter, up 19.5%. The Resale Price Index slipped 0.1%, its third small fall in a row. The talk quoted the earlier flash figures, about 7,500 deals and a 0.2% dip.
The extra demand sat in five-room and executive flats. Huttons' count has five-room deals up 26.7% and executive flats up about 42%. The likely cause is the end of the 15-month wait-out on 28 July 2026. Private owners can now buy a resale flat straight away, as long as they sell their private home first. Many are right-sizing from a condo or a landed home into a large flat. Our analysis of the wait-out removal covers the conditions attached.
That also explains the record. 597 flats sold for $1 million or more, the first quarter above 500. Most were in mature towns: Toa Payoh had 93, Queenstown 86 and Bukit Merah 56. Others were newer flats in Bidadari and Dawson, with long leases left and layouts that need little renovation. Still, 597 is about 8% of the quarter's deals. More than nine in ten flats sold for less. The million-dollar flat is a real segment, not the market.
Who is paying today's prices?
The talk named three groups, and their money explains a lot. HDB upgraders sell a flat that has gained in value and get their CPF back, so they carry real equity into the next home. Right-sizers, often older owners, sell a large home and buy a smaller one to free cash for retirement. And parents who right-size often pass part of that cash to their children for a first home. Marcus called it family wealth transfer.
This is the deck's most useful point for anyone worried about a crash: buyers with equity and family help do not have to sell when the market softens. The catch is one the talk did not stress. All three groups depend on a sale to fund the next purchase. Upgraders depend on HDB resale prices, and those have dipped for three quarters running. The dips are small, but if they continue, the cash upgraders bring to a new launch shrinks too. That is the number I would watch in 2027.
Why do this year's land bids matter for 2027 prices?
Because land is the first cost in every new home, and the land for 2027's launches has already been bought at higher rates. ERA's research puts the rise in land rates over about four years at roughly 40% in the CCR, 60% in the RCR and 25% in the OCR. Launch prices rose too, but more slowly than land. That gap has to close, either through higher launch prices or thinner developer margins.
Three record bids this year show the floor moving up:
- Berlayar Drive, near Keppel Bay (RCR), closed in August at $1,515 psf ppr.
- New Upper Changi Road in Bedok (OCR) closed in September at $1,537 psf ppr, a record for the OCR. Our tender result analysis walks through it.
- Lorong Puntong off Sin Ming Avenue, near Bright Hill MRT (RCR), closed in September at $1,612 psf ppr, a record for the RCR.
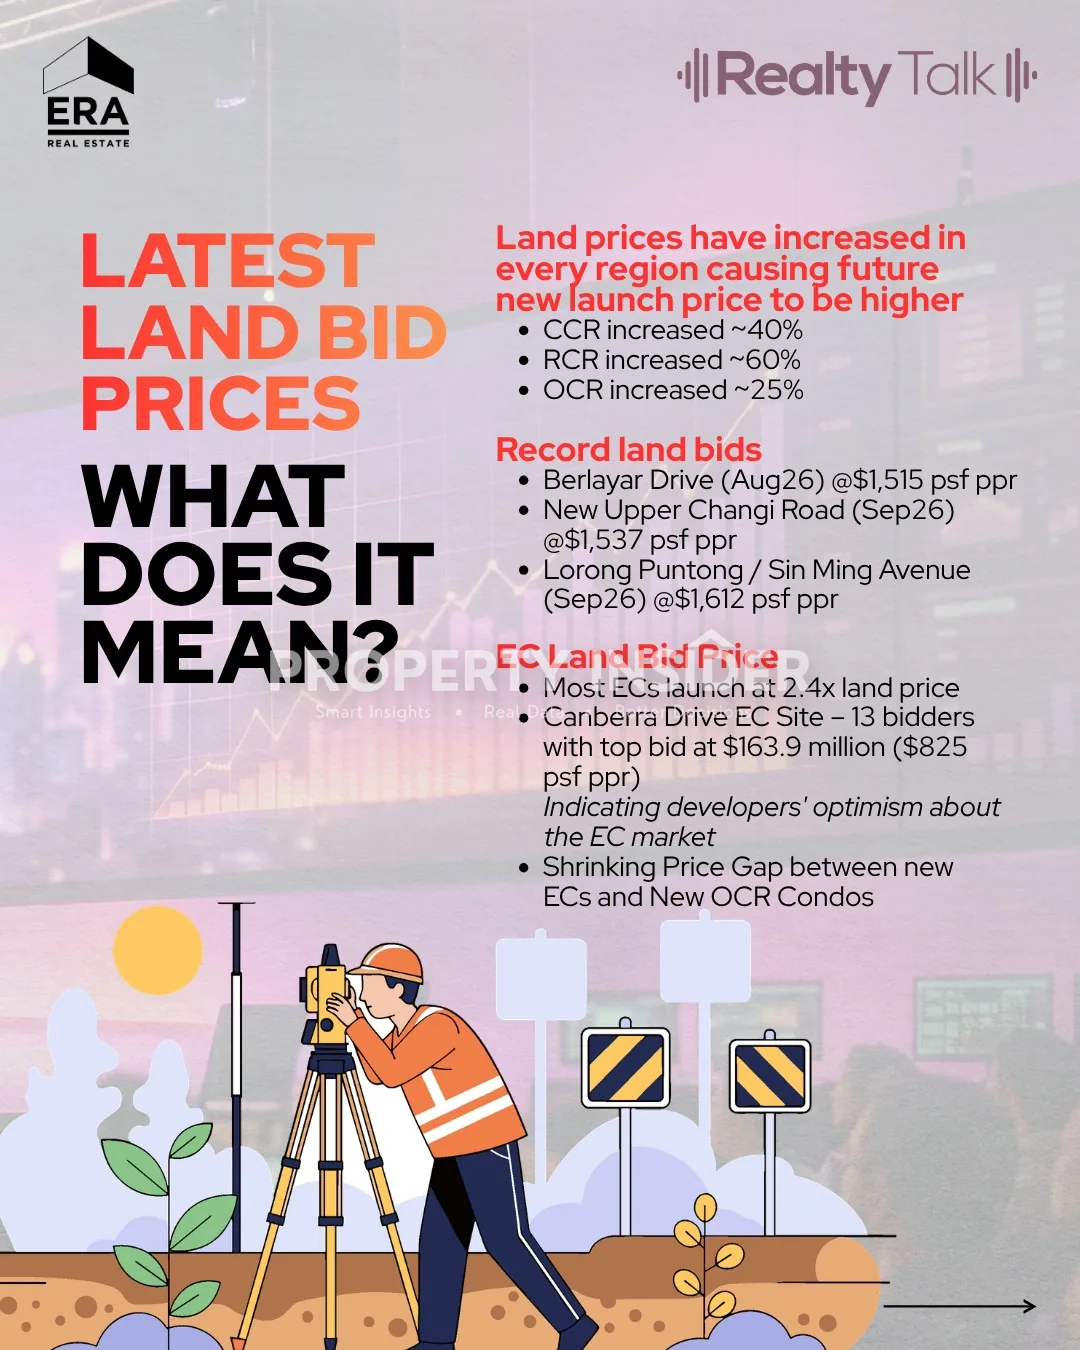
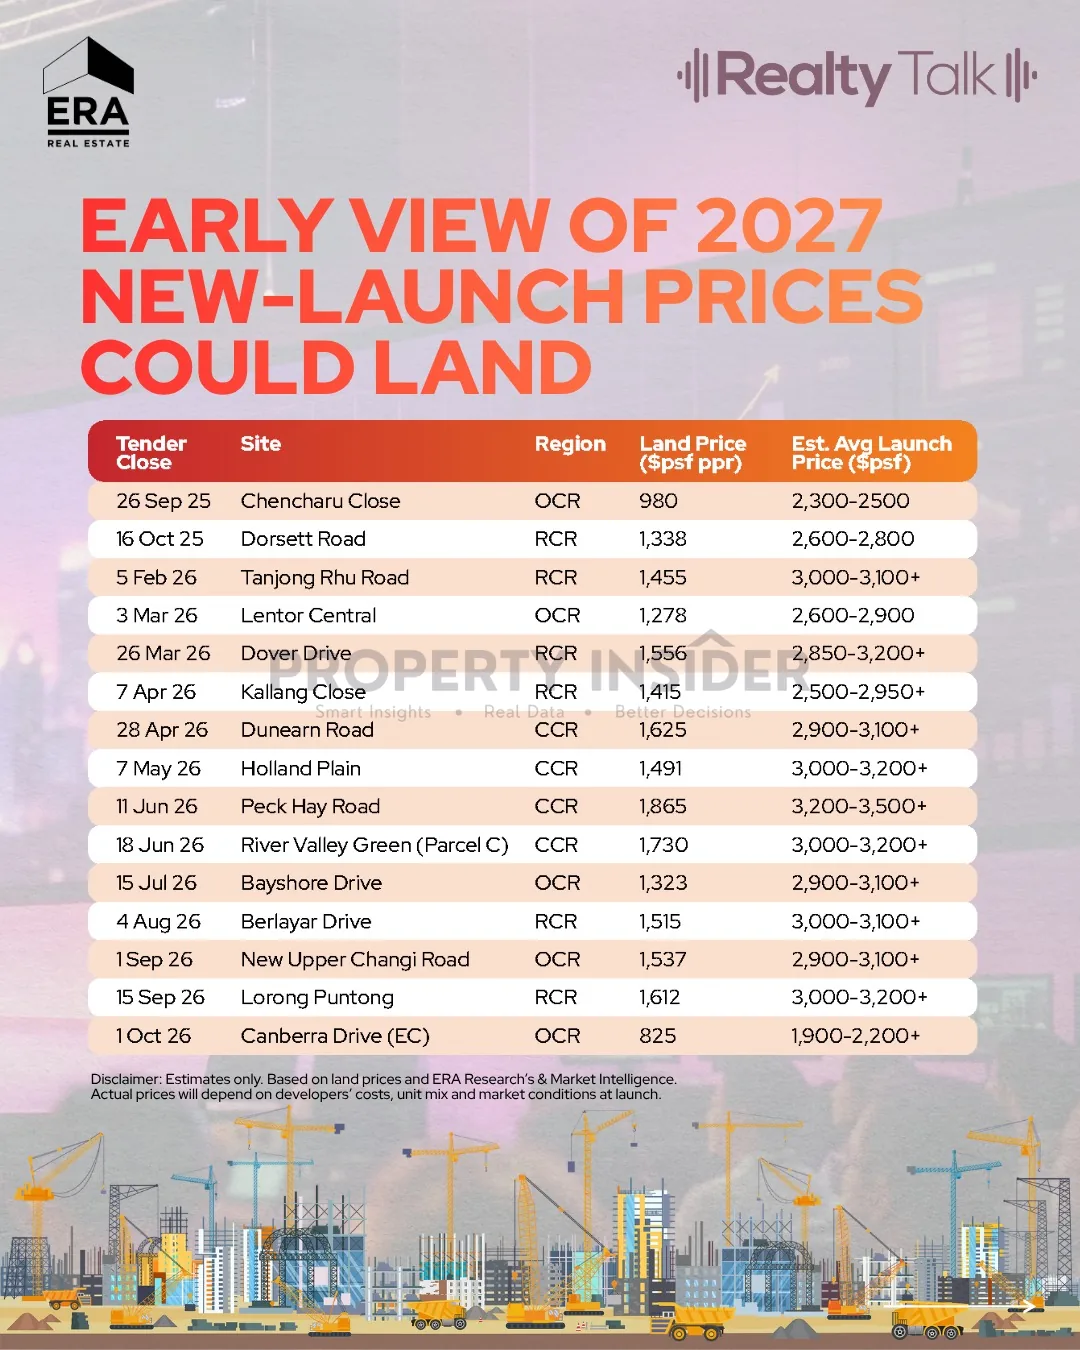
A developer usually takes a year or more to get approvals and open a showflat. So sites sold in 2026 mostly launch from late 2027. The table below sets ERA's early view against our own estimates for the same sites.
| Site | Region | Land, psf ppr | ERA early view | Our estimate (est.) |
|---|---|---|---|---|
| Chencharu Close | OCR | 980 | 2,300–2,500 | 2,270–2,560 |
| Dorset Gardens (Dorset Road) | RCR | 1,338 | 2,600–2,800 | 2,840–3,210 |
| Tanjong Rhu Road | RCR | 1,455 | 3,000–3,100+ | 3,020–3,420 |
| Lentor Signature (Lentor Central) | OCR | 1,278 | 2,600–2,900 | 2,740–3,100 |
| Dover Drive | RCR | 1,556 | 2,850–3,200+ | 3,180–3,600 |
| Kallang Close | RCR | 1,415 | 2,500–2,950+ | 2,960–3,340 |
| Dunearn Road | CCR | 1,625 | 2,900–3,100+ | 3,290–3,720 |
| Holland Plain | CCR | 1,491 | 3,000–3,200+ | 3,080–3,480 |
| Peck Hay Road | CCR | 1,865 | 3,200–3,500+ | 3,670–4,150 |
| River Valley Green (Parcel C) | CCR | 1,730 | 3,000–3,200+ | 3,460–3,910 |
| Bayshore Drive | OCR | 1,323 | 2,900–3,100+ | 2,810–3,180 |
| Berlayar Drive | RCR | 1,515 | 3,000–3,100+ | 3,100–3,510 |
| New Upper Changi Road | OCR | 1,537 | 2,900–3,100+ | 3,150–3,560 |
| Lorong Puntong | RCR | 1,612 | 3,000–3,200+ | Not yet published |
| Canberra Drive (EC) | OCR | 825 | 1,900–2,200+ | 1,900–2,150 |
Two research desks, working separately, land in the same place. Of the 14 sites where both have a figure, the middle of our range sits above the middle of ERA's at 12. The biggest gaps are in the prime districts, Peck Hay Road and River Valley Green, where we are about $560 to $590 psf higher. Our estimates start from the breakeven, which is the land plus construction, finance, fees and marketing, then add the 15% to 30% margin developers have historically taken. The method is on our pricing methodology page and every cost stack is on the land cost tracker. These estimates are not developer-confirmed.
Is $3,000 psf really the 2027 norm?
For most RCR and CCR launches, I think yes, and Thomson Reserve made the case stronger, not weaker. Before its launch we estimated $2,380 to $2,690 psf. It sold 1,143 of 1,268 homes over 30 and 31 October at an average of $2,900 psf, 7.8% above the top of our range. Our launch review logs that as a miss. When a big project clears at a price above its cost model, developers holding dearer land have little reason to price below their own.
Here is the counter-case. Land cost sets a floor for the developer, not a ceiling for you. Developers cut margins when sales stall, and they have done it before. The weak new-home sales this quarter are a reminder that buyers do walk away when a price feels wrong. The talk itself noted that well-located projects at the right price sold out this year, while others still had units left. A record land bid tells you what the next launch would like to charge, not what it is worth to you.
What does the Canberra Drive record say about ECs?
It says developers still want EC land under the tougher rules, but they disagree sharply on its value. The Canberra Drive site closed on 1 October with 13 bids, the most for an EC site in eight years. The top bid was $163.9 million, about $825 psf ppr, the highest ever paid for EC land. The lowest was about $361 psf ppr, and six bids came in above $700. Our tender analysis has the full field.
ERA's rule of thumb is that ECs launch at about 2.4 times their land price. At $825, that points to around $1,900 to $2,200 psf, and our own estimate of $1,900 to $2,150 psf agrees. The Canberra Drive site is also the first sold under the rules that took effect on 8 May 2026: a ten-year MOP instead of five, no deferred payment scheme, and nine in ten launch-day units kept for first-timers. Our guide to the new EC rules explains each one.
The gap between new ECs and private OCR condos is narrowing. On ERA's figures, ECs bought around 2021 were about 38% cheaper than OCR condos. Today, with EC median prices around $1,845 psf, that gap is about 26%. Eugene's view in the talk was that a household near the top of the EC income range should now compare an OCR condo seriously, because the condo has no ten-year lock. Marcus's view was that for middle-income families, an EC is still the more affordable route. Both are right for different households. One addition: the income ceiling for new ECs rose from $16,000 to $18,000 on 24 August 2026, but it is tied to the land site. Check the ceiling for the specific project with HDB before you plan around it.
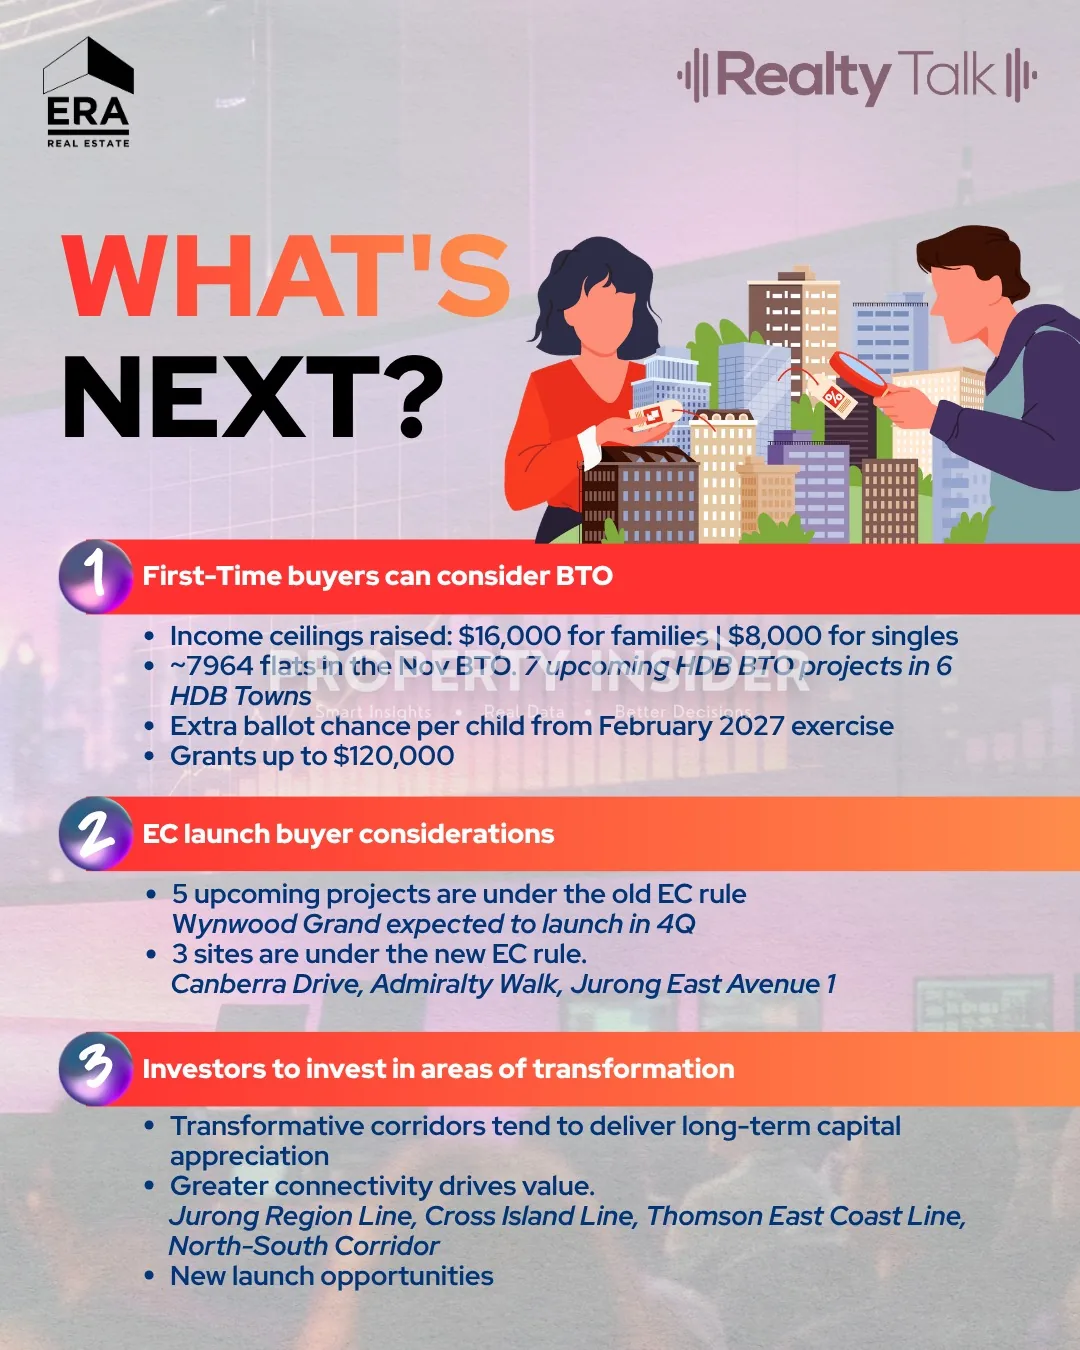
Several ECs on sites sold before 8 May 2026 are still to launch under the old rules, with a five-year MOP and the deferred payment scheme. ERA counts five. Wynwood Grand, with 430 homes, is the next one, with a preview planned for 11 December 2026 on our tracker. Once that pipeline sells, every new EC carries the ten-year rule. That is a real deadline, though it is measured in launches, not in calendar days.
What has changed since the talk?
Four things have moved since 29 October.
- The November BTO has come and gone. HDB offered 7,964 flats in seven projects across six towns, including two Bayshore projects and Toa Payoh Hillside next to Caldecott MRT, the only Prime project. Applications closed on 11 November. The next exercise is in February 2027, and that is the first one with an extra ballot chance for each child in first-timer families.
- Thomson Reserve sold 90% on launch weekend, at the $2,900 psf average above. The talk said its prices were close to resale at JadeScape nearby. On our records, Thomson Reserve's average is about 24% above JadeScape's median resale price of $2,341 psf over the past year. Matched floor for floor against Grand Dunman, a similar new project, the price of a two-bedder is about the same. Both comparisons are fair; they answer different questions.
- The Thomson-East Coast Line will be complete on 26 December 2026. LTA confirmed that Bedok South and Sungei Bedok open that day. The RTS Link from Woodlands North to Johor Bahru is now targeted for February 2027, subject to safety approvals.
- One date in the talk needs correcting. The Cross Island Line interchange at Bright Hill is officially targeted for 2030, as part of Phase 1, not 2032.
Should you make your move before 2026 ends?
Only if your own numbers are ready. The year-end date matters less than it sounds. Here is how I would read the window for each type of buyer.
| If you are | What the signal says | What to check first |
|---|---|---|
| A first-time BTO applicant | The November window has closed. February 2027 adds an extra ballot chance per child, so families gain by waiting for it | Your HFE letter, and whether a Plus or Prime flat's longer MOP suits you |
| Eligible for an EC | The old-rule ECs are the real deadline. Once they sell, every EC carries a ten-year MOP | Which rules and income ceiling apply to that project's land site |
| An HDB upgrader | Today's launches sit on cheaper land than 2027's. Your flat's resale price has softened slightly | The cash gap between your sale proceeds and the new home's downpayment, using our affordability calculator |
| A private owner right-sizing to HDB | No more 15-month wait. Large resale flats are in demand, so expect competition | You must sell the private home first |
| An investor | ERA's view is that areas with new rail lines and planned growth tend to hold value better over time | Rental demand and resale prices nearby, not the launch brochure |
My view: for an upgrader who has found the right home at today's launch prices, waiting for 2027 mostly means paying land costs that have already gone up. For everyone else, the only deadline that cannot be moved is the one set by your own finances and family plans. The talk's closing line was that timing the market rarely works, but projects that tick every box come round only once in a while. I would put it more simply. Buy when the home fits and the numbers hold. Do not buy because a calendar says December.
The short version
What to take away from the third quarter
- Private pricesUp 1.4%, led by landed homes, on 24% fewer deals. A real rise, on thin trading
- HDB resale7,645 deals, up 19.5%, while prices dipped 0.1%. Bigger flats did the selling
- Million-dollar flatsA record 597, about 8% of deals. Most flats still sell below $1 million
- LandRecord bids in the OCR, RCR and EC segments. Most 2027 launches estimated near or above $2,900 psf (est.)
- ECsCanberra Drive set an EC land record at $825 psf ppr. The old-rule pipeline is the last five-year-MOP stock
- The windowThe November BTO has closed. The EC deadline is real. For private buyers, readiness matters more than the date
So what should you do with this? Work out your cash gap first, before you visit a showflat. Then, for any 2027 project you are waiting for, compare its estimated price on our upcoming launches list with what is on sale now. If the newer project only beats today's option by being newer, today's option may be the better buy.
Frequently asked questions
Why did Singapore private home prices rise in 3Q 2026 while sales fell?
URA's price index rose 1.4% in the third quarter of 2026, the fastest rise in almost two years, while ERA counted about 4,700 private deals, 24% fewer than the quarter before. Landed homes led the rise at 2.8%. Volume fell because developers launched only three projects during the Lunar seventh month, and they sold 1,183 new homes against 2,141 in the second quarter.
Are HDB resale prices falling in 2026?
Slightly. HDB's Resale Price Index fell 0.1% in the third quarter of 2026, its third small decline in a row. Transactions rose 19.5% to 7,645, led by five-room and executive flats after the 15-month wait-out for private owners was removed on 28 July 2026.
How many million-dollar HDB flats were sold in 3Q 2026?
A record 597, the first time the quarterly count passed 500. They were about 8% of resale deals, so most flats still sold below $1 million. Toa Payoh had the most, with 93, followed by Queenstown with 86 and Bukit Merah with 56.
Will new launch prices be higher in 2027?
Most likely, for sites sold at 2026 land rates. Record bids include $1,537 psf ppr at New Upper Changi Road and $1,612 psf ppr at Lorong Puntong. PropertyInsider.sg estimates most RCR and CCR launches from these sites at about $2,900 to $3,600 psf, and ERA's early view is in a similar range. These are estimates, not developer-confirmed prices, and developers can still cut margins if sales are slow.
What was the Canberra Drive EC land price?
The Canberra Drive EC site drew 13 bids when its tender closed on 1 October 2026. The top bid was $163.9 million, about $825 psf ppr, the highest ever paid for EC land. It is the first EC site sold under the rules that took effect on 8 May 2026, so its homes will carry a ten-year minimum occupation period. Launch prices are estimated at about $1,900 to $2,150 psf.
Should I buy an EC before the new rules apply to all launches?
It depends on your income, your plans for the next ten years and whether you qualify. ECs on land sold before 8 May 2026, such as Wynwood Grand, keep the five-year MOP and the deferred payment scheme. Once that pipeline sells, every new EC carries the ten-year rule. Check each project's rules and income ceiling with HDB before planning around them.
Is it better to buy a new launch now or wait until 2027?
That depends on your cash, your loan limit and how long you will hold, and nothing here is financial advice. Today's launches are priced off land bought at lower rates than the sites launching in 2027, which favours buying when the right home appears. The case for waiting is a larger choice of projects in 2027, and the chance that slow sales push developers to accept thinner margins.
Sources & methodology
How we checked this
Every market figure from the talk was checked against the official release it came from. Where HDB's final third-quarter figures differ from the flash estimates quoted on 29 October, this column uses the final figures and says so. The launch-price estimates in the comparison table are PropertyInsider.sg's own, read from our project records on 19 November 2026; ERA's figures are copied from its slide as shown. Thomson Reserve's sales, average price and the JadeScape and Grand Dunman comparisons come from our launch review of 2 November 2026, which uses the developers' price and availability lists and URA caveat records.
Where the figures come from
ERA Singapore, Realty Talk, "Reading the Signals: Making Your Move Before 2026 End", 29 October 2026, presented by Marcus Chu and Eugene Lim, drawing on URA, HDB and ERA Research and Market Intelligence. URA, Release of 3rd Quarter 2026 real estate statistics, 23 October 2026. HDB, Resale Price Index table, third quarter 2026. HDB, November 2026 sales launch. LTA, TEL Stage 5 and DTL3 Extension opening, 4 November 2026, and RTS Link service targeted for February 2027, 2 October 2026. LTA, the next phase of rail development, March 2026, for the Cross Island Line Phase 1 target. Huttons' flat-type counts as reported by EdgeProp and Stacked Homes, October 2026. Income ceilings as announced at the National Day Rally on 23 August 2026, effective 24 August 2026. Figures marked (est.) and every launch estimate are analyst estimates under our pricing methodology, not developer-confirmed.
Page history
- 19 Nov 2026: first published. HDB's final third-quarter figures (7,645 deals, a 0.1% dip) replace the flash figures quoted in the talk. The Cross Island Line date is corrected to 2030. Post-talk events added: the November BTO, Thomson Reserve's launch weekend, and the TEL Stage 5 and RTS Link dates.
- Next update: after URA and HDB release fourth-quarter 2026 flash estimates in early January 2027, and when Wynwood Grand's prices are published.
Eligibility questions about BTO flats, ECs and grants should go to HDB. Nothing on this page is financial or property advice. The author is a licensed property consultant with ERA, which is one of the joint marketing agencies for Thomson Reserve; that interest is declared in the note at the top of this column and in our editorial policy.